Skip to the screening

Materiality Navigator·Solid Waste Management Utilities

Which topics should you investigate first?

Choose a business model to see the candidate sustainability topics most likely to need investigation, and why. Then refine the shortlist, work through each topic and record a preliminary screening decision.

This is an industry-informed hypothesis. Your task is to test it against the organisation's impacts, dependencies, risks, opportunities and stakeholder evidence. Industry relevance does not make a topic material.

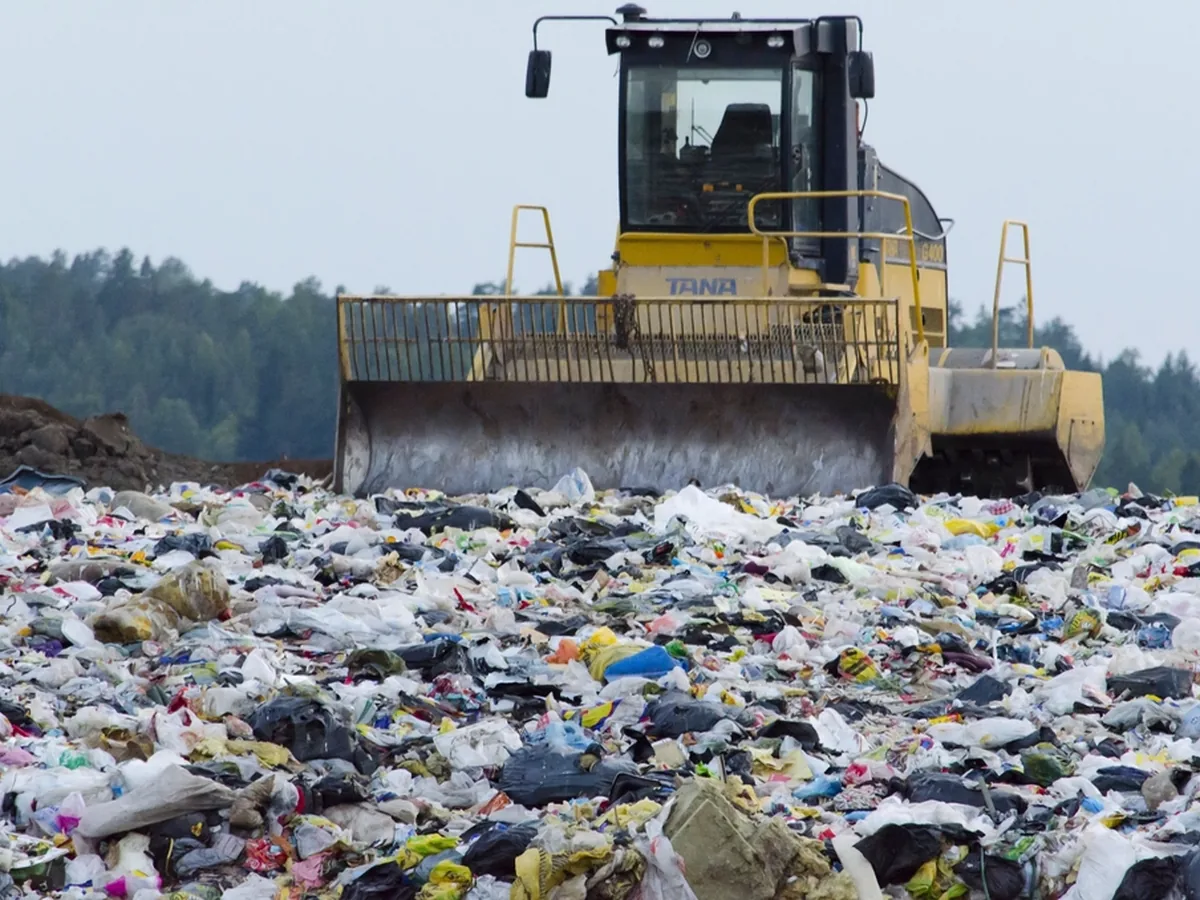
A landfill compactor spreading household waste at a landfill site.
Step 1 Choose the business model you are screening

Candidate topics — Solid Waste Management Utilities

  • Environment
  • Industry baseline
  • Strong industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Routine non-greenhouse-gas air pollutant emissions from waste collection vehicles, flares, refuse-derived fuel preparation, energy-from-waste operations and ash handling, including stack emissions, diesel exhaust, particulates, acid gases, mercury and dioxins.

How it shows up in this industry

Energy-from-waste plants, refuse-derived fuel lines, boilers, turbines, flares, ash handling systems and collection fleets can emit nitrogen oxides, sulphur dioxide, particulates, mercury, dioxins, acid gases, diesel exhaust and brake-wear particles. Industrial emissions permits, continuous monitoring and Best Available Techniques influence reagent use, residue handling, plant availability and local acceptance of thermal treatment capacity.

Why it may be material

For operators with energy recovery, flaring or dense vehicle fleets, routine air emissions performance drives permit continuity, abatement capital expenditure, reagent and residue disposal costs, unplanned outages, enforcement penalties and opposition to new or expanded facilities.

Impact pathway

  1. Potential effects may reach the atmosphere.
  2. Potential effects may reach affected communities.
  3. Potential effects may reach ecosystems.
  4. Potential effects may reach workers.
  5. Potential effects may reach future generations.
  6. Affected stakeholder groups identified in the source include Affected communities, Contractors, Employees.
  7. The source places the pathway in Own operations, Downstream.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  4. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  5. The topic may affect insurance availability, coverage terms, premiums or claims.
  6. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  7. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • What is the scale, scope, likelihood and remediability of effects on the atmosphere?
  • What is the scale, scope, likelihood and remediability of effects on affected communities?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Emissions, air-quality and atmospheric-impact records linked to the topic
  • Community engagement, grievance and impact records
  • Biodiversity, habitat and ecosystem-impact evidence
  • Workforce, health and safety, engagement and grievance records
  • Long-term scenario, cumulative-impact and intergenerational analysis
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Insurance coverage, premium, exclusion and claims records
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Rear-loader, side-loader and front-loader refuse collection vehicles, including diesel, CNG, electric and hybrid fleets
  • Process-map item (assets): Landfill cells with engineered liners, leachate collection, gas wells, daily cover systems, capping and long-term monitoring boreholes
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant downstream pathway.

Affected stakeholders

  • Affected communities
  • Contractors
  • Employees

Users of the information

  • Board / management
  • Investors / creditors
  • Local authorities
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Environment
  • Industry baseline
  • Strong industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Environmental impacts associated with how effectively the operator moves waste up the hierarchy through collection design, source separation, materials recovery facility sorting, organic waste treatment, construction and demolition sorting, and recovery-route allocation before downstream output quality or final-destination assurance is assessed.

How it shows up in this industry

The industry collects residual, recycling, garden, food, commercial and construction waste and processes it through transfer stations, materials recovery facilities, organic waste treatment, construction and demolition sorting, refuse-derived fuel lines and other recovery routes. Circular economy policies, landfill restrictions, food waste separation and EPR create demand for higher capture rates and lower reject rates at collection and sorting stages.

Why it may be material

The waste hierarchy is a defining impact pathway for this industry. Poor collection design, weak source separation and inefficient sorting increase residual disposal, incineration and primary extraction burdens, while stronger recovery performance diverts paper, metals, plastics, glass, wood, organic waste and aggregates towards productive use and supports municipal recycling targets.

Impact pathway

  1. Potential effects may reach ecosystems.
  2. Potential effects may reach the atmosphere.
  3. Potential effects may reach water bodies.
  4. Potential effects may reach soil and groundwater.
  5. Potential effects may reach future generations.
  6. Affected stakeholder groups identified in the source include Business partners, Customers / end-users, Suppliers.
  7. The source places the pathway in Own operations, Upstream, Cross value chain.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  4. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  5. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which upstream activities, suppliers or inputs create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What is the scale, scope, likelihood and remediability of effects on ecosystems?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Biodiversity, habitat and ecosystem-impact evidence
  • Emissions, air-quality and atmospheric-impact records linked to the topic
  • Water withdrawal, discharge, quality and catchment-impact records
  • Soil and groundwater monitoring, incident and remediation records
  • Long-term scenario, cumulative-impact and intergenerational analysis
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Materials recovery facilities with screens, magnets, eddy current separators, optical sorters, ballistic separators and manual picking lines
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (customers): Municipal authorities procuring household collection, street cleansing, recycling and disposal services

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant upstream pathway.

Affected stakeholders

  • Business partners
  • Customers / end-users
  • Suppliers

Users of the information

  • Investors / creditors
  • Local authorities
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Environment
  • Industry baseline
  • Strong industry signal
  • Double materiality
  • Cross-cutting

Workcard generated from the catalogue

What this topic covers

Prevention, monitoring and remediation of unintended soil, groundwater and surface water contamination from landfills, transfer stations, treatment pads and waste storage areas, with emphasis on liner integrity, capping, release response and long-term aftercare.

How it shows up in this industry

Landfill cells, engineered liners, leachate pipework, gas wells, final caps, settlement areas, monitoring boreholes and stormwater systems create long-dated exposure to soil, groundwater and surface water contamination. Liner failure, cap cracking, settlement, unauthorised waste acceptance or historic disposal practices can create remediation and aftercare obligations long after a site stops accepting waste.

Why it may be material

The financial exposure is long-tail and asset-specific: release incidents or legacy contamination can increase remediation liabilities, closure and post-closure provisions, insurance pricing, financing scrutiny, permit restrictions and impairment of landfill assets or surrounding land.

Impact pathway

  1. Potential effects may reach water bodies.
  2. Potential effects may reach soil and groundwater.
  3. Potential effects may reach ecosystems.
  4. Potential effects may reach affected communities.
  5. Potential effects may reach future generations.
  6. Affected stakeholder groups identified in the source include Affected communities.
  7. The source places the pathway in Own operations.

Financial pathway

  1. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  2. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  3. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  4. The topic may affect insurance availability, coverage terms, premiums or claims.
  5. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  6. The topic may affect access to finance, funding terms or the cost of capital.
  7. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • What is the scale, scope, likelihood and remediability of effects on water bodies?
  • What is the scale, scope, likelihood and remediability of effects on soil and groundwater?
  • What is the scale, scope, likelihood and remediability of effects on ecosystems?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Water withdrawal, discharge, quality and catchment-impact records
  • Soil and groundwater monitoring, incident and remediation records
  • Biodiversity, habitat and ecosystem-impact evidence
  • Community engagement, grievance and impact records
  • Long-term scenario, cumulative-impact and intergenerational analysis
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Insurance coverage, premium, exclusion and claims records
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Funding terms, lender or investor requirements and cost-of-capital analysis
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Landfill cells with engineered liners, leachate collection, gas wells, daily cover systems, capping and long-term monitoring boreholes
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (assets): Permits, municipal concessions, franchise contracts, landfill void rights, environmental monitoring data and local operating relationships
  • Process-map item (emerging_pressures): Mandatory food waste separation and landfill bans increasing demand for organics collection and anaerobic digestion capacity

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.

Affected stakeholders

  • Affected communities

Users of the information

  • Board / management
  • Investors / creditors
  • Local authorities
  • NGOs / civil society
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Environment
  • Industry baseline
  • Strong industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Protection of surface water, groundwater and soil through routine management of leachate, contaminated runoff, sediment and treated effluent generated by landfills, transfer stations, organics infrastructure and waste processing sites.

How it shows up in this industry

Landfills, transfer stations, composting pads, construction and demolition processing areas and waste treatment sites operate leachate collection systems, stormwater drains, monitoring boreholes, settlement ponds and effluent treatment. Mixed waste, fines, organics, contaminated soils and treatment sludges can mobilise ammonia, metals, nutrients, organics, plastics and persistent chemicals into receiving environments if routine controls fail.

Why it may be material

Water and groundwater pathways are central for landfill and waste handling assets. Leachate and stormwater performance affects treatment operating cost, discharge compliance, closure provisions, local water users, permit resilience, insurance and long-term asset value.

Impact pathway

  1. Potential effects may reach water bodies.
  2. Potential effects may reach soil and groundwater.
  3. Potential effects may reach ecosystems.
  4. Potential effects may reach affected communities.
  5. Potential effects may reach future generations.
  6. Affected stakeholder groups identified in the source include Affected communities.
  7. The source places the pathway in Own operations, Downstream.

Financial pathway

  1. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  2. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  3. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  4. The topic may affect insurance availability, coverage terms, premiums or claims.
  5. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  6. The topic may affect access to finance, funding terms or the cost of capital.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • What is the scale, scope, likelihood and remediability of effects on water bodies?
  • What is the scale, scope, likelihood and remediability of effects on soil and groundwater?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Water withdrawal, discharge, quality and catchment-impact records
  • Soil and groundwater monitoring, incident and remediation records
  • Biodiversity, habitat and ecosystem-impact evidence
  • Community engagement, grievance and impact records
  • Long-term scenario, cumulative-impact and intergenerational analysis
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Insurance coverage, premium, exclusion and claims records
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Funding terms, lender or investor requirements and cost-of-capital analysis
  • Process-map item (assets): Transfer stations with tipping halls, compactors, balers, odour controls, weighbridges and stormwater management
  • Process-map item (assets): Landfill cells with engineered liners, leachate collection, gas wells, daily cover systems, capping and long-term monitoring boreholes
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant downstream pathway.

Affected stakeholders

  • Affected communities

Users of the information

  • Investors / creditors
  • Local authorities
  • NGOs / civil society
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Environment
  • Industry baseline
  • Strong industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Management of contamination, testing, sorting accuracy, specification compliance and safe end use for recovered materials and treatment by-products produced by waste management operations.

How it shows up in this industry

Materials recovery facilities use screens, magnets, eddy current separators, optical sorters, ballistic separators and manual picking lines to produce paper, cardboard, metal, plastics, glass and wood outputs. Organics sites produce compost, soil improver and digestate, while energy-from-waste and construction processing generate bottom ash aggregates, refuse-derived fuel and residues that require testing and controlled destinations.

Why it may be material

Output quality directly affects revenue, downgrading, rejection, disposal cost, customer claims, access to reprocessors, producer responsibility reporting value and capital allocation to optical sorting, robotics, depackaging and contamination analytics. It also determines whether circular outputs protect downstream users and ecosystems.

Impact pathway

  1. Potential effects may reach downstream users.
  2. Potential effects may reach consumers.
  3. Potential effects may reach ecosystems.
  4. Potential effects may reach water bodies.
  5. Potential effects may reach soil and groundwater.
  6. Potential effects may reach affected communities.
  7. Affected stakeholder groups identified in the source include Affected communities, Business partners, Customers / end-users, Suppliers.
  8. The source places the pathway in Own operations, Downstream, Cross value chain.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  4. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  5. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  6. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What is the scale, scope, likelihood and remediability of effects on downstream users?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Downstream-user outcome, complaint and product-use evidence
  • Consumer outcome, complaint and product-impact records
  • Biodiversity, habitat and ecosystem-impact evidence
  • Water withdrawal, discharge, quality and catchment-impact records
  • Soil and groundwater monitoring, incident and remediation records
  • Community engagement, grievance and impact records
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Rear-loader, side-loader and front-loader refuse collection vehicles, including diesel, CNG, electric and hybrid fleets
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Organics infrastructure including in-vessel composting, windrow pads, anaerobic digestion tanks, pasteurisation and biogas upgrading units
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (customers): Reprocessors, paper mills, metal smelters, plastics recyclers, compost users and energy utilities buying recovered outputs

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant downstream pathway.

Affected stakeholders

  • Affected communities
  • Business partners
  • Customers / end-users
  • Suppliers

Users of the information

  • Investors / creditors
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Environment
  • Industry baseline
  • Strong industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Management of greenhouse gas emissions and transition economics across landfill methane, landfill gas monitoring, diesel and CNG fleets, energy-from-waste combustion and anaerobic digestion, including technology choices, carbon cost exposure and low-carbon service positioning.

How it shows up in this industry

Waste management operators have material greenhouse gas exposure through methane from landfill cells, gas wells, daily cover, capping defects and organics handling, as well as diesel and CNG refuse collection vehicles and carbon dioxide from energy-from-waste plants. Remote methane detection, carbon pricing, methane fees, landfill levies, biomethane incentives and municipal climate requirements increasingly affect asset economics and tender performance.

Why it may be material

This is a core issue because landfill gas, collection fleets and thermal treatment are central operating features of the industry. Capture performance, fuel choices and verified methane data affect climate impacts, operating cost, carbon charges, energy revenue, concession scoring, financing scrutiny and long-term landfill aftercare obligations.

Impact pathway

  1. Potential effects may reach the atmosphere.
  2. Potential effects may reach affected communities.
  3. Potential effects may reach future generations.
  4. Potential effects may reach workers.
  5. Affected stakeholder groups identified in the source include Affected communities, Customers / end-users.
  6. The source places the pathway in Own operations, Downstream, Cross value chain.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  4. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  5. The topic may affect access to finance, funding terms or the cost of capital.
  6. The topic may affect insurance availability, coverage terms, premiums or claims.
  7. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  8. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What is the scale, scope, likelihood and remediability of effects on the atmosphere?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Emissions, air-quality and atmospheric-impact records linked to the topic
  • Community engagement, grievance and impact records
  • Long-term scenario, cumulative-impact and intergenerational analysis
  • Workforce, health and safety, engagement and grievance records
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Funding terms, lender or investor requirements and cost-of-capital analysis
  • Insurance coverage, premium, exclusion and claims records
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Landfill cells with engineered liners, leachate collection, gas wells, daily cover systems, capping and long-term monitoring boreholes
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (assets): Permits, municipal concessions, franchise contracts, landfill void rights, environmental monitoring data and local operating relationships

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant downstream pathway.

Affected stakeholders

  • Affected communities
  • Customers / end-users

Users of the information

  • Board / management
  • Investors / creditors
  • Local authorities
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Environment
  • Business-model dependent
  • Moderate industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Management of hazardous and special waste streams and hazardous residues generated by waste treatment, including segregation, storage, testing, worker protection, transport interfaces and controlled disposal routes.

How it shows up in this industry

Waste management sites include special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils, and can generate air pollution control residues, fly ash, filter cake, leachate sludges and bottom ash requiring testing and controlled disposal. Persistent chemicals, metals and alkaline dusty residues can materially affect treatment routes, worker protection and customer acceptance.

Why it may be material

Hazardous and special waste handling can generate premium revenue but also drives specialised storage, training, testing and disposal costs, as well as liabilities from mismanagement, residue misclassification, worker exposure, downstream contamination and tighter controls on persistent chemicals.

Impact pathway

  1. Potential effects may reach workers.
  2. Potential effects may reach contractors.
  3. Potential effects may reach affected communities.
  4. Potential effects may reach water bodies.
  5. Potential effects may reach soil and groundwater.
  6. Potential effects may reach ecosystems.
  7. Potential effects may reach downstream users.
  8. Affected stakeholder groups identified in the source include Affected communities, Business partners, Contractors, Customers / end-users, Employees.
  9. The source places the pathway in Own operations, Upstream, Downstream.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  4. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  5. The topic may affect insurance availability, coverage terms, premiums or claims.
  6. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which upstream activities, suppliers or inputs create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • What is the scale, scope, likelihood and remediability of effects on workers?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Workforce, health and safety, engagement and grievance records
  • Contractor working-condition, incident and engagement records
  • Community engagement, grievance and impact records
  • Water withdrawal, discharge, quality and catchment-impact records
  • Soil and groundwater monitoring, incident and remediation records
  • Biodiversity, habitat and ecosystem-impact evidence
  • Downstream-user outcome, complaint and product-use evidence
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Insurance coverage, premium, exclusion and claims records
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Transfer stations with tipping halls, compactors, balers, odour controls, weighbridges and stormwater management
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (customers): Municipal authorities procuring household collection, street cleansing, recycling and disposal services

It may be less material when…

  • The organisation's scale, exposure or effects are below the threshold set for further assessment.
  • The relevant business model, activity, asset or product is not present or is not significant.
  • The organisation has no meaningful exposure to or influence over the relevant upstream or downstream pathway.

Affected stakeholders

  • Affected communities
  • Business partners
  • Contractors
  • Customers / end-users
  • Employees

Users of the information

  • Board / management
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Environment
  • Emerging issue
  • Moderate industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Management of emerging persistent contaminant concerns in organics treatment outputs and landfill leachate, especially where circular products return to soils or water systems.

How it shows up in this industry

Food waste depackaging, composting, anaerobic digestion, pasteurisation and leachate treatment can concentrate contaminants from packaging, sewage-derived co-treatment, WEEE residues, consumer products and mixed organics. Outputs such as compost, soil improver, digestate and treated leachate are increasingly scrutinised where they are applied to land or discharged under permit.

Why it may be material

Mandatory food waste separation and landfill bans are expanding organics treatment capacity, while scientific and regulatory concern over PFAS and microplastics is shifting attention from diversion tonnage to contaminant quality. Operators may face tighter testing, lost agricultural outlets and legacy claims if persistent contaminants are spread through apparently circular outputs.

Impact pathway

  1. Potential effects may reach ecosystems.
  2. Potential effects may reach water bodies.
  3. Potential effects may reach soil and groundwater.
  4. Potential effects may reach affected communities.
  5. Potential effects may reach consumers.
  6. Potential effects may reach future generations.
  7. Affected stakeholder groups identified in the source include Affected communities, Customers / end-users, Suppliers.
  8. The source places the pathway in Own operations, Upstream, Downstream, Cross value chain.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  4. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  5. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  6. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which upstream activities, suppliers or inputs create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Biodiversity, habitat and ecosystem-impact evidence
  • Water withdrawal, discharge, quality and catchment-impact records
  • Soil and groundwater monitoring, incident and remediation records
  • Community engagement, grievance and impact records
  • Consumer outcome, complaint and product-impact records
  • Long-term scenario, cumulative-impact and intergenerational analysis
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Landfill cells with engineered liners, leachate collection, gas wells, daily cover systems, capping and long-term monitoring boreholes
  • Process-map item (assets): Organics infrastructure including in-vessel composting, windrow pads, anaerobic digestion tanks, pasteurisation and biogas upgrading units
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (customers): Reprocessors, paper mills, metal smelters, plastics recyclers, compost users and energy utilities buying recovered outputs
  • Process-map item (emerging_pressures): Mandatory food waste separation and landfill bans increasing demand for organics collection and anaerobic digestion capacity

It may be less material when…

  • The organisation's scale, exposure or effects are below the threshold set for further assessment.
  • The organisation has no meaningful exposure to or influence over the relevant upstream or downstream pathway.
  • The emerging signal has not yet created a relevant exposure, impact or financial effect for the organisation.

Affected stakeholders

  • Affected communities
  • Customers / end-users
  • Suppliers

Users of the information

  • Investors / creditors
  • Local authorities
  • NGOs / civil society
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Environment
  • Emerging issue
  • Moderate industry signal
  • Double materiality
  • Cross-cutting

Workcard generated from the catalogue

What this topic covers

Adaptation of waste collection, treatment and disposal infrastructure to flooding, heat, storms, wildfire and water stress that can compromise containment, worker safety and service delivery.

How it shows up in this industry

Waste management sites combine exposed outdoor operations, engineered landfill liners, leachate collection, gas wells, tipping halls, composting pads, vehicle depots, energy-from-waste plants, anaerobic digestion tanks and urban collection routes. Flooding, heatwaves and storms can mobilise leachate, damage caps, interrupt collections, increase odour and pest burdens and create heat stress for crews working around heavy vehicles.

Why it may be material

Physical climate hazards are becoming more material as landfill aftercare periods extend over decades and municipalities expect uninterrupted essential waste services. The issue links adaptation investment, worker safety, pollution prevention, insurance and service continuity in a way that is increasingly scrutinised by lenders and public authorities.

Impact pathway

  1. Potential effects may reach workers.
  2. Potential effects may reach contractors.
  3. Potential effects may reach affected communities.
  4. Potential effects may reach water bodies.
  5. Potential effects may reach soil and groundwater.
  6. Potential effects may reach ecosystems.
  7. Potential effects may reach emergency responders.
  8. Potential effects may reach future generations.
  9. Affected stakeholder groups identified in the source include Affected communities, Contractors, Customers / end-users, Employees.
  10. The source places the pathway in Own operations, Downstream, Cross value chain.

Financial pathway

  1. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may affect insurance availability, coverage terms, premiums or claims.
  4. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  5. The topic may affect demand, pricing, market access or product and service revenue.
  6. The topic may affect access to finance, funding terms or the cost of capital.
  7. The topic may create provisions, penalties, remediation costs, claims or other liabilities.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What is the scale, scope, likelihood and remediability of effects on workers?
  • What scientific evidence or consensus could change the topic's relevance?

Evidence to collect

  • Workforce, health and safety, engagement and grievance records
  • Contractor working-condition, incident and engagement records
  • Community engagement, grievance and impact records
  • Water withdrawal, discharge, quality and catchment-impact records
  • Soil and groundwater monitoring, incident and remediation records
  • Biodiversity, habitat and ecosystem-impact evidence
  • Emergency-response plans, incident logs and responder feedback
  • Long-term scenario, cumulative-impact and intergenerational analysis
  • Capital plans, asset adaptation budgets and investment approvals
  • Operating-cost records and budgets linked to the topic
  • Insurance coverage, premium, exclusion and claims records
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Funding terms, lender or investor requirements and cost-of-capital analysis
  • Provision, claim, penalty, remediation and contingent-liability records
  • Process-map item (assets): Rear-loader, side-loader and front-loader refuse collection vehicles, including diesel, CNG, electric and hybrid fleets
  • Process-map item (assets): Landfill cells with engineered liners, leachate collection, gas wells, daily cover systems, capping and long-term monitoring boreholes
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Organics infrastructure including in-vessel composting, windrow pads, anaerobic digestion tanks, pasteurisation and biogas upgrading units
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils

It may be less material when…

  • The organisation's scale, exposure or effects are below the threshold set for further assessment.
  • The organisation has no meaningful exposure to or influence over the relevant downstream pathway.
  • The emerging signal has not yet created a relevant exposure, impact or financial effect for the organisation.

Affected stakeholders

  • Affected communities
  • Contractors
  • Customers / end-users
  • Employees

Users of the information

  • Investors / creditors
  • Local authorities
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Social
  • Industry baseline
  • Strong industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Management of occupational injury and public road safety exposures in collection, transfer, sorting, landfill, organics, construction and demolition waste processing and maintenance activities.

How it shows up in this industry

Waste operations involve frequent urban vehicle movements, reversing and lifting equipment, compactors, balers, manual picking lines, weighbridges, landfill working faces and exposure to sharps, bioaerosols and contaminated bins. Collection crews, drivers, agency workers, mechanics and contractors work around moving traffic, mobile plant and unpredictable waste contents.

Why it may be material

This industry combines mobile heavy vehicles, contaminated materials, manual handling, mechanical sorting, maintenance and outdoor landfill work. Poor safety performance increases compensation, claims, insurance premiums, absence, overtime, recruitment cost, contract penalties and reputational damage in public procurement.

Impact pathway

  1. Potential effects may reach workers.
  2. Potential effects may reach contractors.
  3. Potential effects may reach affected communities.
  4. Potential effects may reach emergency responders.
  5. Affected stakeholder groups identified in the source include Contractors, Employees, Trade unions.
  6. The source places the pathway in Own operations, Upstream.

Financial pathway

  1. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  2. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  3. The topic may affect insurance availability, coverage terms, premiums or claims.
  4. The topic may affect demand, pricing, market access or product and service revenue.
  5. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which upstream activities, suppliers or inputs create or concentrate the pathway?
  • What is the scale, scope, likelihood and remediability of effects on workers?
  • What is the scale, scope, likelihood and remediability of effects on contractors?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Workforce, health and safety, engagement and grievance records
  • Contractor working-condition, incident and engagement records
  • Community engagement, grievance and impact records
  • Emergency-response plans, incident logs and responder feedback
  • Operating-cost records and budgets linked to the topic
  • Provision, claim, penalty, remediation and contingent-liability records
  • Insurance coverage, premium, exclusion and claims records
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Rear-loader, side-loader and front-loader refuse collection vehicles, including diesel, CNG, electric and hybrid fleets
  • Process-map item (assets): Landfill cells with engineered liners, leachate collection, gas wells, daily cover systems, capping and long-term monitoring boreholes
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant upstream pathway.

Affected stakeholders

  • Contractors
  • Employees
  • Trade unions

Users of the information

  • Board / management
  • Local authorities
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Social
  • Industry baseline
  • Strong industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Management of local amenity, wellbeing and fairness concerns around waste facilities and collection routes, including odour, noise, litter, pests, traffic disturbance, visual amenity, engagement and grievance response.

How it shows up in this industry

Landfills, transfer stations, tipping halls, composting windrows, anaerobic digestion tanks, materials recovery facilities, energy-from-waste plants and collection routes can create odour, noise, traffic, litter, vermin, gulls, dust and perceived health concerns. Waste infrastructure also depends on municipal concessions, permits and long-term local operating relationships, making cumulative community burdens and fairness in siting increasingly material.

Why it may be material

Fence-line communities experience repeated disturbance from waste handling and vehicle movements even where permitted emission limits are met. Community opposition can delay planning, restrict permits, increase odour control and traffic management spending, reduce municipal contract renewal prospects and lower the value of strategically located assets.

Impact pathway

  1. Potential effects may reach affected communities.
  2. Potential effects may reach Indigenous peoples.
  3. Potential effects may reach workers.
  4. Potential effects may reach contractors.
  5. Potential effects may reach ecosystems.
  6. Affected stakeholder groups identified in the source include Affected communities.
  7. The source places the pathway in Own operations, Downstream.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  3. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  4. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  5. The topic may affect access to finance, funding terms or the cost of capital.
  6. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  7. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • What is the scale, scope, likelihood and remediability of effects on affected communities?
  • What is the scale, scope, likelihood and remediability of effects on Indigenous peoples?
  • What civil-society scrutiny or campaigns could change the topic's relevance?

Evidence to collect

  • Community engagement, grievance and impact records
  • Indigenous engagement, consent, grievance and impact records
  • Workforce, health and safety, engagement and grievance records
  • Contractor working-condition, incident and engagement records
  • Biodiversity, habitat and ecosystem-impact evidence
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Operating-cost records and budgets linked to the topic
  • Provision, claim, penalty, remediation and contingent-liability records
  • Funding terms, lender or investor requirements and cost-of-capital analysis
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Transfer stations with tipping halls, compactors, balers, odour controls, weighbridges and stormwater management
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Organics infrastructure including in-vessel composting, windrow pads, anaerobic digestion tanks, pasteurisation and biogas upgrading units
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant downstream pathway.

Affected stakeholders

  • Affected communities

Users of the information

  • Board / management
  • Investors / creditors
  • Local authorities
  • Media
  • NGOs / civil society
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Social
  • Industry baseline
  • Strong industry signal
  • Double materiality
  • Cross-cutting

Workcard generated from the catalogue

What this topic covers

Prevention and emergency control of fires, explosions, smoke releases and contaminated firewater caused by hazardous or stored-energy items entering waste collection, transfer, sorting, storage and reprocessing pathways.

How it shows up in this industry

Collection rounds, transfer station tipping halls and materials recovery facility sorting lines increasingly receive hidden lithium-ion batteries from WEEE, vapes, power tools and household devices, along with gas cylinders, hot ashes and chemicals. Compaction, shredding and baling can initiate thermal runaway or rupture, spreading fires through mixed waste piles and recyclate bales and creating contaminated firewater.

Why it may be material

Waste operators cannot fully control what customers place in bins and skips. Mis-sorted batteries, cylinders and chemicals create a coherent safety, pollution, insurance and continuity pathway spanning collection, bulking, sorting, storage, emergency response and downstream bale quality.

Impact pathway

  1. Potential effects may reach workers.
  2. Potential effects may reach contractors.
  3. Potential effects may reach affected communities.
  4. Potential effects may reach emergency responders.
  5. Potential effects may reach water bodies.
  6. Potential effects may reach soil and groundwater.
  7. Potential effects may reach the atmosphere.
  8. Potential effects may reach downstream users.
  9. Affected stakeholder groups identified in the source include Affected communities, Business partners, Contractors, Employees.
  10. The source places the pathway in Own operations, Upstream, Downstream, Cross value chain.

Financial pathway

  1. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  2. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  3. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  4. The topic may affect insurance availability, coverage terms, premiums or claims.
  5. The topic may affect demand, pricing, market access or product and service revenue.
  6. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  7. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which upstream activities, suppliers or inputs create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What technology changes could alter the topic's impacts or financial effects?

Evidence to collect

  • Workforce, health and safety, engagement and grievance records
  • Contractor working-condition, incident and engagement records
  • Community engagement, grievance and impact records
  • Emergency-response plans, incident logs and responder feedback
  • Water withdrawal, discharge, quality and catchment-impact records
  • Soil and groundwater monitoring, incident and remediation records
  • Emissions, air-quality and atmospheric-impact records linked to the topic
  • Downstream-user outcome, complaint and product-use evidence
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Insurance coverage, premium, exclusion and claims records
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Transfer stations with tipping halls, compactors, balers, odour controls, weighbridges and stormwater management
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (customers): Households using kerbside residual, recycling, garden waste, bulky waste and food waste services

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant upstream or downstream pathway.
  • The emerging signal has not yet created a relevant exposure, impact or financial effect for the organisation.

Affected stakeholders

  • Affected communities
  • Business partners
  • Contractors
  • Employees

Users of the information

  • Board / management
  • Investors / creditors
  • Local authorities
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Social
  • Emerging issue
  • Moderate industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Workforce transition associated with artificial intelligence, robotics and digital analytics in waste collection, sorting and contamination control, with secondary governance considerations for accountable human oversight of automated decisions that shape worker tasks or customer interactions.

How it shows up in this industry

Materials recovery facilities increasingly combine optical sorters, robotic arms, ballistic separators, telematics, bin sensors and contamination photographs with manual quality control. These systems can reduce direct manual picking of mixed recyclables and residual waste, while changing maintenance skills, line supervision, work pace, agency labour demand and customer-facing tasks linked to contamination notices.

Why it may be material

Digital sorting and waste tracking are moving from experimental projects to procurement-relevant capabilities, driven by contamination control, labour availability, bale quality and reporting needs under producer responsibility schemes. The topic is primarily material where operators have sizeable manual sorting teams or customer-facing contamination workflows and must manage redeployment, training and worker consultation rather than treating technology only as a productivity investment.

Impact pathway

  1. Potential effects may reach workers.
  2. Potential effects may reach contractors.
  3. Potential effects may reach supply-chain workers.
  4. Potential effects may reach downstream users.
  5. Affected stakeholder groups identified in the source include Contractors, Customers / end-users, Employees, Trade unions.
  6. The source places the pathway in Own operations, Cross value chain.

Financial pathway

  1. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  2. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  3. The topic may affect demand, pricing, market access or product and service revenue.
  4. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What is the scale, scope, likelihood and remediability of effects on workers?
  • What is the scale, scope, likelihood and remediability of effects on contractors?
  • What technology changes could alter the topic's impacts or financial effects?

Evidence to collect

  • Workforce, health and safety, engagement and grievance records
  • Contractor working-condition, incident and engagement records
  • Supplier workforce, audit, grievance and remediation records
  • Downstream-user outcome, complaint and product-use evidence
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Materials recovery facilities with screens, magnets, eddy current separators, optical sorters, ballistic separators and manual picking lines
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (customers): Households using kerbside residual, recycling, garden waste, bulky waste and food waste services

It may be less material when…

  • The organisation's scale, exposure or effects are below the threshold set for further assessment.
  • The emerging signal has not yet created a relevant exposure, impact or financial effect for the organisation.

Affected stakeholders

  • Contractors
  • Customers / end-users
  • Employees
  • Trade unions

Users of the information

  • Board / management
  • Investors / creditors
  • Local authorities

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Governance
  • Industry baseline
  • Strong industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Governance of how waste operators bid for, price, report and comply with municipal concessions, franchise contracts, public procurement requirements and environmental permits for essential waste services.

How it shows up in this industry

Waste management utilities rely on municipal authorities procuring household collection, street cleansing, recycling and disposal services, and they hold permits, concessions, franchise contracts, landfill void rights and environmental monitoring data. Gate fees, collection charges, contract indexation, weighbridge data and permit compliance determine how costs and service quality affect households, ratepayers and local environments.

Why it may be material

Public waste services are essential local infrastructure in a heavily regulated setting. Poor integrity in bidding, billing, weighing, reporting or permit compliance can shift costs to households, distort siting and treatment choices, weaken environmental controls and lead to fines, debarment, contract loss and financing damage.

Impact pathway

  1. Potential effects may reach affected communities.
  2. Potential effects may reach consumers.
  3. Potential effects may reach downstream users.
  4. Potential effects may reach ecosystems.
  5. Potential effects may reach water bodies.
  6. Potential effects may reach soil and groundwater.
  7. Affected stakeholder groups identified in the source include Affected communities, Customers / end-users, Employees.
  8. The source places the pathway in Own operations, Downstream, Cross value chain.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  3. The topic may affect reputation, licences to operate, intellectual property or other intangible value.
  4. The topic may affect access to finance, funding terms or the cost of capital.
  5. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  6. The topic may change operating costs through resource use, controls, remediation or ongoing management.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What is the scale, scope, likelihood and remediability of effects on affected communities?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Community engagement, grievance and impact records
  • Consumer outcome, complaint and product-impact records
  • Downstream-user outcome, complaint and product-use evidence
  • Biodiversity, habitat and ecosystem-impact evidence
  • Water withdrawal, discharge, quality and catchment-impact records
  • Soil and groundwater monitoring, incident and remediation records
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Provision, claim, penalty, remediation and contingent-liability records
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Funding terms, lender or investor requirements and cost-of-capital analysis
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Operating-cost records and budgets linked to the topic
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (assets): Permits, municipal concessions, franchise contracts, landfill void rights, environmental monitoring data and local operating relationships
  • Process-map item (customers): Municipal authorities procuring household collection, street cleansing, recycling and disposal services

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant downstream pathway.

Affected stakeholders

  • Affected communities
  • Customers / end-users
  • Employees

Users of the information

  • Board / management
  • Investors / creditors
  • Local authorities
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Governance
  • Industry baseline
  • Strong industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Governance of waste provenance, classification, transfer records, consignment notes, contamination data, haulier and broker controls, destination assurance and cross-border movement controls to prevent leakage into unsafe or unlawful pathways.

How it shows up in this industry

Waste operators rely on weighbridge ticketing, duty of care records, waste transfer notes, hazardous waste consignment notes, customer portals, contamination photographs, carrier controls and digital tracking systems. Special streams such as asbestos, WEEE, batteries, chemicals, clinical waste and contaminated soils, alongside exports of recyclates and refuse-derived fuel, require accurate segregation, documentation, destination checks and Basel-related controls.

Why it may be material

Incorrect classification or weak destination assurance can move contamination away from the generator and into unsuitable treatment, illegal disposal, unsafe reprocessing or uncontrolled export routes. It can also cause rejected loads, enforcement penalties, contract termination, revenue loss and reputational damage.

Impact pathway

  1. Potential effects may reach affected communities.
  2. Potential effects may reach ecosystems.
  3. Potential effects may reach water bodies.
  4. Potential effects may reach soil and groundwater.
  5. Potential effects may reach downstream users.
  6. Potential effects may reach supply-chain workers.
  7. Potential effects may reach future generations.
  8. Affected stakeholder groups identified in the source include Affected communities, Business partners, Customers / end-users, Suppliers.
  9. The source places the pathway in Own operations, Upstream, Downstream, Cross value chain.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  4. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  5. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.
  6. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which upstream activities, suppliers or inputs create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Community engagement, grievance and impact records
  • Biodiversity, habitat and ecosystem-impact evidence
  • Water withdrawal, discharge, quality and catchment-impact records
  • Soil and groundwater monitoring, incident and remediation records
  • Downstream-user outcome, complaint and product-use evidence
  • Supplier workforce, audit, grievance and remediation records
  • Long-term scenario, cumulative-impact and intergenerational analysis
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Transfer stations with tipping halls, compactors, balers, odour controls, weighbridges and stormwater management
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (customers): Households using kerbside residual, recycling, garden waste, bulky waste and food waste services

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant upstream or downstream pathway.
  • The emerging signal has not yet created a relevant exposure, impact or financial effect for the organisation.

Affected stakeholders

  • Affected communities
  • Business partners
  • Customers / end-users
  • Suppliers

Users of the information

  • Investors / creditors
  • Local authorities
  • NGOs / civil society
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Governance
  • Business-model dependent
  • Moderate industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Governance of lobbying, political contributions, trade association activity and public policy engagement affecting waste hierarchy regulation, producer responsibility, landfill economics, incineration, export controls and infrastructure permitting.

How it shows up in this industry

Waste operators are affected by and often engage on landfill tax, disposal levies, EPR, deposit return schemes, food waste separation, landfill bans, incineration permitting, transboundary waste controls and municipal procurement rules. Advocacy positions can influence the balance between prevention, recycling, recovery and disposal, as well as the cost allocation between producers, municipalities and households.

Why it may be material

Public policy engagement is material because regulatory design directly shapes gate fees, contract economics, asset utilisation, landfill void values, energy-from-waste demand and recycling investment. Misaligned lobbying can undermine stated circularity or climate objectives and attract regulatory, investor and civil society scrutiny.

Impact pathway

  1. Potential effects may reach affected communities.
  2. Potential effects may reach ecosystems.
  3. Potential effects may reach water bodies.
  4. Potential effects may reach the atmosphere.
  5. Potential effects may reach future generations.
  6. Affected stakeholder groups identified in the source include Customers / end-users.
  7. The source places the pathway in Own operations, Downstream, Cross value chain.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  4. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  5. The topic may affect access to finance, funding terms or the cost of capital.
  6. The topic may affect reputation, licences to operate, intellectual property or other intangible value.
  7. The topic may affect asset useful lives, impairment assumptions, valuations or stranded-asset exposure.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What is the scale, scope, likelihood and remediability of effects on affected communities?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Community engagement, grievance and impact records
  • Biodiversity, habitat and ecosystem-impact evidence
  • Water withdrawal, discharge, quality and catchment-impact records
  • Emissions, air-quality and atmospheric-impact records linked to the topic
  • Long-term scenario, cumulative-impact and intergenerational analysis
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Funding terms, lender or investor requirements and cost-of-capital analysis
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Asset valuations, useful-life assumptions, impairment tests and stranded-asset analysis
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (customers): Households using kerbside residual, recycling, garden waste, bulky waste and food waste services
  • Process-map item (customers): Retail, hospitality, office and leisure businesses needing scheduled bin, compactor and food waste collections

It may be less material when…

  • The organisation's scale, exposure or effects are below the threshold set for further assessment.
  • The relevant business model, activity, asset or product is not present or is not significant.
  • The organisation has no meaningful exposure to or influence over the relevant downstream pathway.

Affected stakeholders

  • Customers / end-users

Users of the information

  • Board / management
  • Investors / creditors
  • Local authorities
  • Media
  • NGOs / civil society
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Governance
  • Emerging issue
  • Strong industry signal
  • Double materiality

Workcard generated from the catalogue

What this topic covers

Governance of the operational data and chain-of-custody evidence used to allocate producer responsibility fees, validate recycling outcomes and support deposit return, WEEE, battery or packaging scheme reporting.

How it shows up in this industry

Waste operators provide collection, weighing, sorting, contamination checks, bale quality data and duty of care documentation for packaging, WEEE, batteries and deposit return systems. Modulated fees and producer-funded schemes increase the value of accurate evidence on material flows, rejected contamination and final destinations.

Why it may be material

EPR and deposit return regimes are shifting cost and accountability from municipal taxpayers towards producers, while waste companies hold the operational evidence needed to allocate fees and prove recycling outcomes. Poor data controls can create revenue leakage, customer disputes and allegations of inflated recycling or recovery claims.

Impact pathway

  1. Potential effects may reach downstream users.
  2. Potential effects may reach affected communities.
  3. Potential effects may reach ecosystems.
  4. Potential effects may reach water bodies.
  5. Potential effects may reach supply-chain workers.
  6. Affected stakeholder groups identified in the source include Business partners, Customers / end-users, Suppliers.
  7. The source places the pathway in Own operations, Upstream, Downstream, Cross value chain.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  4. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  5. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which upstream activities, suppliers or inputs create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What current or proposed regulation could change the topic's relevance?

Evidence to collect

  • Downstream-user outcome, complaint and product-use evidence
  • Community engagement, grievance and impact records
  • Biodiversity, habitat and ecosystem-impact evidence
  • Water withdrawal, discharge, quality and catchment-impact records
  • Supplier workforce, audit, grievance and remediation records
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Transfer stations with tipping halls, compactors, balers, odour controls, weighbridges and stormwater management
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (assets): Permits, municipal concessions, franchise contracts, landfill void rights, environmental monitoring data and local operating relationships

It may be less material when…

  • Organisation-specific evidence does not support significant scale, severity, likelihood or financial effect.
  • The organisation has no meaningful exposure to or influence over the relevant upstream or downstream pathway.
  • The emerging signal has not yet created a relevant exposure, impact or financial effect for the organisation.

Affected stakeholders

  • Business partners
  • Customers / end-users
  • Suppliers

Users of the information

  • Board / management
  • Investors / creditors
  • Local authorities
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

  • Governance
  • Emerging issue
  • Moderate industry signal
  • Double materiality
  • Cross-cutting

Workcard generated from the catalogue

What this topic covers

Governance of cybersecurity, data integrity and operational resilience for digital systems used in collection routing, customer service, weighbridge records, waste tracking, contamination analytics and automated sorting.

How it shows up in this industry

Waste operators increasingly depend on digital route planning, vehicle telematics, bin sensors, customer portals, weighbridge ticketing, contamination photographs, waste tracking systems and automated sorting controls. Disruption or manipulation of these systems can interrupt collections, distort waste provenance records, affect billing and expose customer or service data.

Why it may be material

Digitalisation is becoming central to efficient collections, compliance reporting, producer responsibility evidence and materials recovery. Cyber incidents can create missed collections, public service disruption, inaccurate duty of care records, privacy claims, insurance impacts and loss of trust from municipalities and commercial customers.

Impact pathway

  1. Potential effects may reach affected communities.
  2. Potential effects may reach workers.
  3. Potential effects may reach contractors.
  4. Potential effects may reach downstream users.
  5. Affected stakeholder groups identified in the source include Contractors, Customers / end-users, Employees.
  6. The source places the pathway in Own operations, Upstream, Downstream, Cross value chain.

Financial pathway

  1. The topic may affect demand, pricing, market access or product and service revenue.
  2. The topic may change operating costs through resource use, controls, remediation or ongoing management.
  3. The topic may require capital expenditure to adapt assets, processes or infrastructure.
  4. The topic may create provisions, penalties, remediation costs, claims or other liabilities.
  5. The topic may affect insurance availability, coverage terms, premiums or claims.
  6. The topic may affect reputation, licences to operate, intellectual property or other intangible value.

Questions to test

  • What evidence supports both the impact and financial materiality pathways?
  • Which own operations, assets or decisions create or concentrate the pathway?
  • Which upstream activities, suppliers or inputs create or concentrate the pathway?
  • Which products, services, customers or end uses create or concentrate the pathway?
  • Where across the value chain is the pathway most significant?
  • What technology changes could alter the topic's impacts or financial effects?

Evidence to collect

  • Community engagement, grievance and impact records
  • Workforce, health and safety, engagement and grievance records
  • Contractor working-condition, incident and engagement records
  • Downstream-user outcome, complaint and product-use evidence
  • Revenue, demand, pricing and market-access analysis linked to the topic
  • Operating-cost records and budgets linked to the topic
  • Capital plans, asset adaptation budgets and investment approvals
  • Provision, claim, penalty, remediation and contingent-liability records
  • Insurance coverage, premium, exclusion and claims records
  • Reputation, licence-to-operate, intellectual-property and other intangible-value evidence
  • Process-map item (assets): Energy-from-waste plants, refuse-derived fuel preparation lines, boilers, turbines, flue gas treatment and ash handling systems
  • Process-map item (assets): Special waste storage bays for asbestos, chemicals, WEEE, batteries, clinical waste and contaminated soils
  • Process-map item (assets): Digital route planning, vehicle telematics, bin sensors, customer portals, waste tracking systems and contamination analytics
  • Process-map item (assets): Permits, municipal concessions, franchise contracts, landfill void rights, environmental monitoring data and local operating relationships
  • Process-map item (customers): Households using kerbside residual, recycling, garden waste, bulky waste and food waste services

It may be less material when…

  • The organisation's scale, exposure or effects are below the threshold set for further assessment.
  • The organisation has no meaningful exposure to or influence over the relevant upstream or downstream pathway.
  • The emerging signal has not yet created a relevant exposure, impact or financial effect for the organisation.

Affected stakeholders

  • Contractors
  • Customers / end-users
  • Employees

Users of the information

  • Board / management
  • Investors / creditors
  • Local authorities
  • Regulators

Standards to check

Your preliminary screening decision

Saved in this browser. Your notes leave it only when you export the screening.

An initial screening — not a materiality assessment

To turn a shortlist into a defensible result, you still need to:

  • engage affected stakeholders
  • assess severity and likelihood
  • evaluate financial effects
  • define thresholds
  • document governance and approval
  • keep an audit trail
How this screening is built, and what it is not

Candidate topics come from the LRA materiality topic catalogue (18 topics for this industry that passed quality checks), aligned to GRI sector numbering and the SASB SICS classification.

Topics, rationales, impact and financial channels, stakeholders and standard hints come from the reviewed catalogue. Workcards and activity matches are generated from it by fixed rules; where LRA has written a workcard or a disclosure mapping by hand, it is labelled as curated.

Your selections, decisions and notes stay in this browser. They are sent to LRA only to build an Excel file when you choose to export, and are not stored.

This is an educational screening aid. It is not issued or endorsed by GRI, the IFRS Foundation, EFRAG or SASB, and it is not a materiality assessment of any organisation.

Initial screening summary

Solid Waste Management Utilities

Organisation profile

    Include for further assessment

      More evidence required

        Provisionally lower priority

          Important limitation. These are screening decisions only. They have not been validated through stakeholder engagement, severity assessment, financial-effect analysis or formal approval.

          The link carries only the sub-industry and the activities you ticked — never your decisions or notes.

          An .xlsx file with your screening, the workcards and the sources for the chosen sub-industry.